For most of the last two decades, the question that decided an Orange County home sale was price. This fall, a second question is muscling its way to the top of the list, and it's catching plenty of buyers and sellers off guard: what does the insurance actually cost, and who is carrying the risk if it goes up again next year?
A Statewide Hike Lands In October
Effective October 15, 2026, the California FAIR Plan — the state's insurer of last resort for homes that traditional carriers won't touch — is raising rates by an average of 29.1% for more than 675,000 policyholders. The FAIR Plan had originally requested 35.8%; the California Department of Insurance approved the lower figure instead. It's the latest jump in a trend that has already pushed California homeowners insurance premiums up 84% since 2020, as wildfire losses and inflation have driven traditional insurers to pull back from higher-risk areas. FAIR Plan enrollment has nearly tripled statewide, from under 2% of homes to about 5%, and total exposure on the plan's books has climbed to roughly $768 billion — a number that dwarfs its cash reserves and leaves it leaning on reinsurance, bonds, and surcharges to cover claims.
Orange County isn't Malibu or Truckee, where roughly half of homes now carry FAIR Plan coverage. But the ripple effects are showing up here in a specific and very local way: through HOA master insurance policies.
Where It Hits Home: Coastal HOAs And Condo Buildings
Condo and townhome buildings don't buy insurance one unit at a time — the HOA carries a master policy covering the building and common areas, and every owner's monthly dues absorb a share of that premium. When a master policy renews at two or three times its previous cost, or a carrier declines to renew at all mid-year, the HOA doesn't get to negotiate the number down. It gets passed through to owners, sometimes as a dues increase and sometimes as a special assessment that can run into hundreds of thousands of dollars depending on the size of the building.
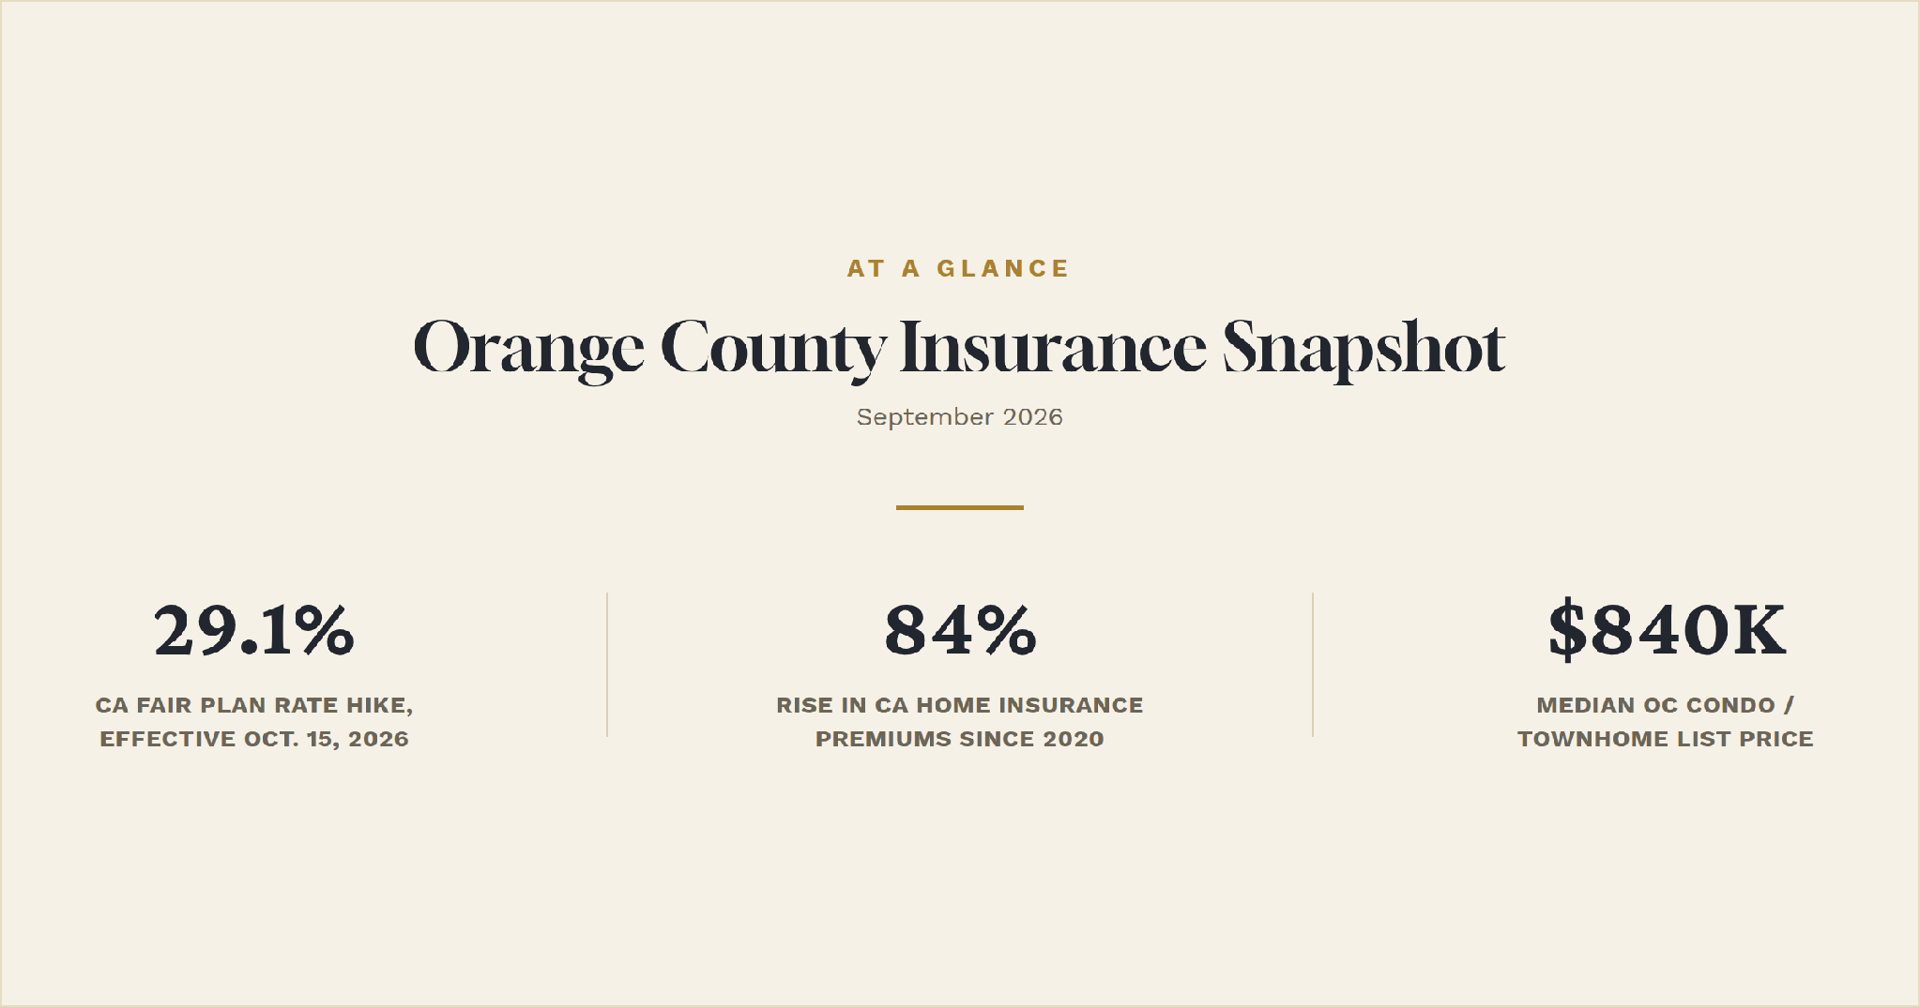
Coastal Orange County communities are feeling this first. Laguna Beach, Newport Beach, Dana Point, and the tightly packed lots of Newport Island and Balboa Island all combine the two ingredients insurers price highest: proximity to open water and older building stock. It isn't limited to the coast, either — larger master-planned communities with shared amenities, like the lakeside clubhouse-and-pool association at Dove Canyon, carry their own master and liability coverage on common facilities, and those premiums are climbing too. Meanwhile, Orange County's condo and townhome segment shows the strain in the numbers: the median list price sits at $840,000, but the median closed price is running noticeably lower — a wider gap than the single-family market is seeing right now, and a sign that financing and insurance friction is doing some of the negotiating for buyers.
What Buyers Should Ask Before They Fall In Love With A Listing
Before writing an offer on any condo or HOA property, ask for the master policy declarations page — the document that spells out coverage limits, the deductible, and the name of the carrier. A deductible above $25,000 to $50,000 is worth a second look, and so is an HOA reserve study that shows the association underfunded relative to its future obligations. An underfunded reserve paired with a rising insurance premium is the exact combination most likely to produce a surprise assessment shortly after you close. It's a five-minute document request that can save a five-figure surprise.
What Sellers Should Do Differently
If you're selling a condo or HOA home this fall, the insurance story is going to surface in the disclosure documents no matter what — buyers' agents are reading master policies more carefully than they were two years ago. The sellers who do best right now are the ones who get ahead of it: disclose accurately, have the HOA's financials and insurance renewal history ready before the first showing, and price with the current insurance and reserve picture already factored in. Transparency closes deals faster than hoping the topic doesn't come up.
Orange County's housing fundamentals haven't changed — inventory is still tight and demand for the right property is still real. But insurance has become a genuine third party at the negotiating table, and the buyers and sellers who understand that this fall will have a real advantage over the ones who don't.
I'm Parisa Houshangi — 25+ years of experience serving Orange County, and proud to rank in the top 1.5% of real estate agents nationwide. If you're navigating a purchase or sale in an HOA or condo community and want a second set of eyes on the insurance picture before you commit, I'm always happy to help.
Keller Williams · OcBeautifulHomes.com · DRE# 01314175