FHA or Conventional? What Orange County First Time Buyers Should Know About Mortgage Insurance
A low down payment can get you in the door, but the type of mortgage insurance you choose decides what you pay and for how long.
If you are buying your first home in Orange County, the down payment is only the start of the conversation. The loan you choose decides how much mortgage insurance you pay, for how long, and whether you can ever get rid of it. Two choices come up most often for first time buyers: an FHA loan and a conventional loan. Here is how they differ, based on current published guidelines, so you can ask your lender sharper questions.
Two Loans, Two Kinds of Mortgage Insurance
A conventional loan with less than 20 percent down usually comes with private mortgage insurance, or PMI. The Consumer Financial Protection Bureau explains that PMI protects the lender, not you, if you stop making payments, and that with 20 percent down it is not required on a conventional loan. An FHA loan is insured by the federal government and carries its own insurance, called the mortgage insurance premium, or MIP. Both cost money. The difference is how the cost is built and how long it lasts.
What FHA Asks For
According to NerdWallet's FHA requirements guide, updated December 22, 2025, the minimum credit score is 500, although lenders often set higher minimums. With a score of 580 or higher, the minimum down payment is 3.5 percent. With a score between 500 and 579, it is 10 percent. A debt to income ratio of 43 percent or below is ideal, but exceptions can be made. That flexibility is why FHA appeals to first time buyers who are still building credit or still saving.
The Part Many Buyers Miss
FHA charges an upfront premium of 1.75 percent of the loan amount at closing, and it can be rolled into the loan. Consider an $820,000 purchase, the median list price for Orange County condos and townhomes in the November 2 market report. A 3.5 percent down payment is $28,700, which leaves a loan of $791,300. The upfront premium on that loan would be about $13,848. That is our arithmetic for illustration, not a quote. There is also an annual premium, which NerdWallet says depends on the length and cost of the loan and the size of your down payment, so ask your lender for the exact figure.
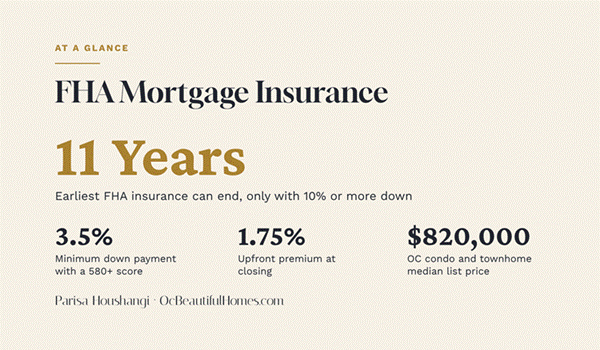
Here is the key difference. With less than 10 percent down, FHA mortgage insurance generally lasts for the life of the loan. With 10 percent or more down, it can be canceled after 11 years. NerdWallet also notes that FHA insurance cannot be canceled simply because you reach 20 percent equity, which is not how private mortgage insurance works. Ask any lender how and when the insurance on each loan can come off.
What This Means in Orange County Right Now
The county's market gives first time buyers some room to work. The November 2 report from Orange County Real Estate, Inc. shows 4,945 active listings, 1,494 pending sales, and a median of 49 days on market. Homes priced under $2.5 million sold an average of 1.9 percent below list, and the report's author notes that inventory is roughly 17 percent above a year ago. The median list price for a single family home is $1,700,000, well above the $1,249,125 conforming loan limit, while condos and townhomes sit near $820,000. FHA loans also have county loan limits, so ask your lender for the current Orange County figure before you shop. In practice, condos and townhomes are where low down payment financing often fits best, and the building itself must meet FHA approval rules.
Rates matter too. Freddie Mac's weekly average for a 30 year fixed mortgage was 7.24 percent as of October 29, down from 7.32 percent the week before and up from 6.17 percent a year ago. Because mortgage insurance is added on top of the rate, compare the total monthly payment and cash needed at closing, not just the rate.
Questions to Ask Your Lender
Ask for FHA and conventional quotes side by side at the same down payment, and compare the monthly payment, the cash needed at closing, and the total insurance cost over the years you expect to keep the loan. Ask how long the insurance lasts under each option, whether a larger down payment changes that, and whether the loan limit fits the price range you are targeting. If you expect to stay a long time or have a stronger credit profile, conventional may cost less over the years. If you need flexibility on credit or cash, FHA may be the better doorway. The right answer depends on your numbers.
This article is general information, not lending or legal advice. Loan guidelines change, so confirm current terms with a licensed lender.
I'm Parisa Houshangi, 25+ years of experience serving Orange County, and proud to rank in the top 1.5% of real estate agents nationwide.
Keller Williams · OcBeautifulHomes.com · DRE# 01314175