When Does PMI Go Away? How Orange County Buyers Can Cancel Private Mortgage Insurance Sooner
Federal rules give private mortgage insurance a firm end date, and a few smart moves can bring that date years closer for Orange County homeowners.
By Parisa Houshangi
If you bought a home in the Orange County housing market with less than 20 percent down on a conventional loan, you are almost certainly paying private mortgage insurance, or PMI. It protects your lender, not you, and it can add a meaningful amount to your monthly payment. The good news is that PMI on a conventional loan is not forever. Federal rules give it a clear end date, and many homeowners can reach that date sooner than they think.
Why So Many Orange County Buyers Carry PMI
Orange County prices make a full 20 percent down payment a tall order. The Orange County Housing Report for November 9, 2026 shows a median list price of $1,699,900 for single family homes and $810,000 for condos and townhomes. On that median condo, 20 percent down is $162,000. Plenty of first time buyers in Irvine, Mission Viejo and Lake Forest choose 5 or 10 percent down instead, accept PMI, and start building equity now rather than waiting years to save more.
Rates matter here too. Freddie Mac's weekly survey put the average 30 year fixed rate at 7.18 percent on November 5, 2026, the third straight weekly decline, though still above the 6.22 percent of a year ago. A higher rate means principal is paid down more slowly in the early years, which pushes back the day PMI can come off. That is exactly why it pays to know the rules.
The Two Numbers to Remember: 80 and 78
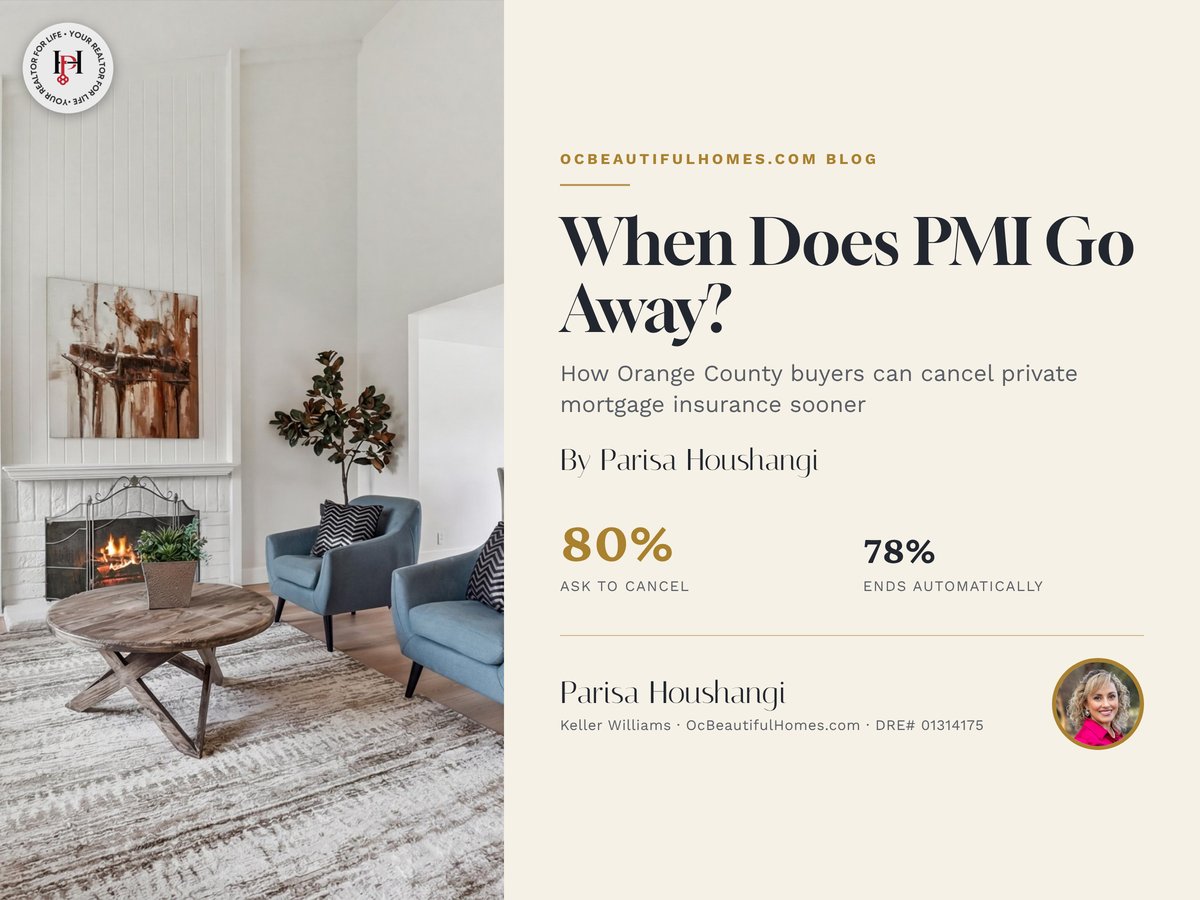
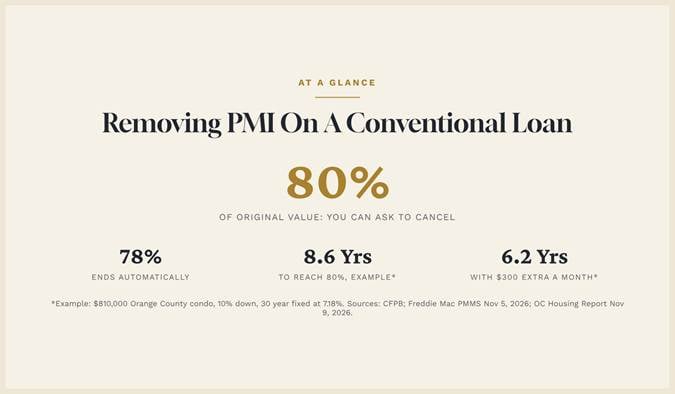
According to the Consumer Financial Protection Bureau, you can ask your servicer to cancel PMI on the date your principal balance is scheduled to fall to 80 percent of the home's original value. That date should appear on the PMI disclosure you received at closing. To qualify, you need to put the request in writing, have a good payment history and be current on your payments, certify there are no junior liens such as a second mortgage, and in some cases show that the home's value has not dropped below its original value, often with an appraisal.
If you never ask, PMI still ends. The servicer must automatically terminate it on the date your balance is scheduled to reach 78 percent of the original value, as long as you are current. And there is a final backstop: PMI must end the month after you reach the midpoint of your loan's amortization schedule, which is 15 years on a 30 year loan, even if you have not hit 78 percent yet.
One detail surprises people. The CFPB explains that original value generally means the lower of the contract sales price or the appraised value at purchase. These federal rules measure progress against that original number, not today's market value.
What That Looks Like on an Orange County Condo
Here is a simple example using local numbers. Say you buy an $810,000 condo with 10 percent down, a $729,000 loan, at 7.18 percent on a 30 year fixed mortgage. On the regular payment schedule, your balance reaches 80 percent of the original value in about 8.6 years, and the automatic 78 percent date arrives in about 9.75 years. Add just $300 a month toward principal and you could reach the 80 percent mark in about 6.2 years. Add $500 a month and it is closer to 5.25 years. The CFPB confirms that extra payments can let you request cancellation ahead of the scheduled date.
Can Rising Home Values Help?
The federal rules are a floor, not a ceiling. The CFPB notes that guidelines from Fannie Mae and Freddie Mac can be more favorable to borrowers, but never less. If your Orange County home has gained value since you bought it, ask your servicer whether your loan's investor allows cancellation based on a new appraisal and what seasoning period applies. Remodels and strong neighborhood sales can sometimes make a real difference, but every servicer has its own process, so get the requirements in writing before you pay for an appraisal.
FHA Loans Follow Different Rules
Everything above applies to conventional loans. FHA mortgage insurance works differently, and the CFPB tells FHA and VA borrowers to check with their servicer for their specific requirements. For many FHA borrowers, refinancing into a conventional loan once they have enough equity is the path to dropping mortgage insurance, so it is worth comparing that option whenever rates ease.
Your Next Step
Pull out your closing documents and find your PMI disclosure. Note your 80 percent date, then look at your latest statement to see how close you are. If you are buying now, ask your lender to show you the PMI schedule before you choose between 5, 10 or 15 percent down. With about 4,900 active listings countywide and homes under $2.5 million selling about 1.4 percent below list, today's buyers have more room to plan their financing carefully. If you would like help running these numbers for a home you own or one you are considering, I am always happy to sit down with you.
I'm Parisa Houshangi, with 25+ years of experience serving Orange County, and proud to rank in the top 1.5% of real estate agents nationwide.
Keller Williams · OcBeautifulHomes.com · DRE# 01314175