Condos and townhomes list for about half the price of Orange County houses, but the lender approves the building as well as the buyer.
By Parisa Houshangi
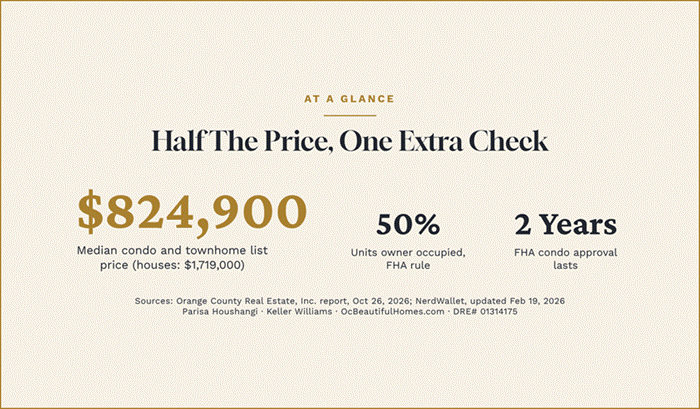
If a house in Orange County feels out of reach, you are not imagining it. In the weekly report from Orange County Real Estate, Inc. dated October 26, 2026, the median list price for a single-family home was $1,719,000. For condos and townhomes it was $824,900, or about 48 percent of the house figure. In the Orange County housing market, that gap is the reason so many first-time buyers, downsizers and move-up sellers looking for a lower-maintenance home start with a condo.
What the market looks like right now
The same report shows 5,054 active listings countywide and 1,522 homes under contract, the fifth straight weekly decline in pending sales. Median days on market held at 47. Homes under $2.5 million closed an average of 1.4 percent below list price. Condos and townhomes that closed in the last seven days had a median price of $690,000, compared with $1,400,000 for houses, though a single week moves around, so the list price is the steadier guide.
Rates are still the headline for most buyers. Freddie Mac reported the average 30-year fixed rate at 7.24 percent on October 29, down from 7.32 percent the week before and up from 6.17 percent a year ago. A lower price means a smaller loan, and that is a large part of the condo appeal.
The extra check: the building
With a house, a lender looks at you and the property. With a condo, the lender also looks at the association. NerdWallet's FHA condo guide, updated February 19, 2026, says at least 50 percent of the units in the project must be owner-occupied, the association should be financially stable with adequate cash reserves, and there should be no pending litigation that could affect the unit's value or lead to a special assessment. FHA condo approvals expire every two years. If a complex is not approved, a lender can request a single-unit approval, which is decided case by case, and NerdWallet notes that FHA relaxed those rules in 2019 but you should still expect paperwork.
Conventional financing has its own screens. JVM Lending says the share of owners behind on dues needs to be under 15 percent in most cases, that one owner holding more than 10 percent of the units often rules out conventional financing, and that rates run higher on condos when the loan is above 75 percent of the value. These sources do not agree on every threshold, and rules vary by lender and loan type, so ask your lender about the specific building before you fall in love with a specific unit.
Monthly dues count against you
Association dues are part of your monthly housing cost, and lenders include them when they calculate your debt-to-income ratio. Here is a hypothetical example. If the dues were $500 a month and a lender capped your total debt at 43 percent of income, which NerdWallet describes as a typical limit with some flexibility for strong applicants, you would need about $1,163 more in gross monthly income to carry those dues ($500 divided by 0.43). That is our arithmetic, not a lender quote, but it shows why two homes with the same price can qualify very differently. JVM Lending notes that lenders require the exact dues figure, so get it in writing early.
Questions to ask before you write an offer
Ask for the association's recent financial statements, its cash reserves and any reserve study. Ask whether a special assessment has been levied or is planned, and whether dues have gone up recently. Ask what share of owners are delinquent, whether the association is in any litigation, and whether the master insurance policy is current. Ask what share of units are owner-occupied versus rented, whether the complex is FHA approved and when that approval expires, what the exact dues and transfer fee are, and whether you can see the governing documents and recent board minutes. Your agent can request these as early as possible so you can review them within your contingency period. Confirm the timelines in your own contract.
If you are selling a condo
Buyers and their lenders will be asking these same questions about your building. Sellers who have the dues, the budget, the reserve information and the FHA approval status ready tend to remove friction before it starts, because a buyer whose lender cannot approve the building cannot close, no matter how much they love your unit. Your agent can help you gather the right documents before you list.
The bottom line
A condo can be the most realistic path into Orange County ownership, and it can be a smart one, as long as you vet the building as carefully as the unit. The price gap is real. So is the extra check.
I'm Parisa Houshangi, 25+ years of experience serving Orange County, and proud to rank in the top 1.5% of real estate agents nationwide.
Keller Williams · OcBeautifulHomes.com · DRE# 01314175